Owner-led practices
Protect senior review time when quarterly preparation starts consuming the working week.
 Discuss a sample quarter
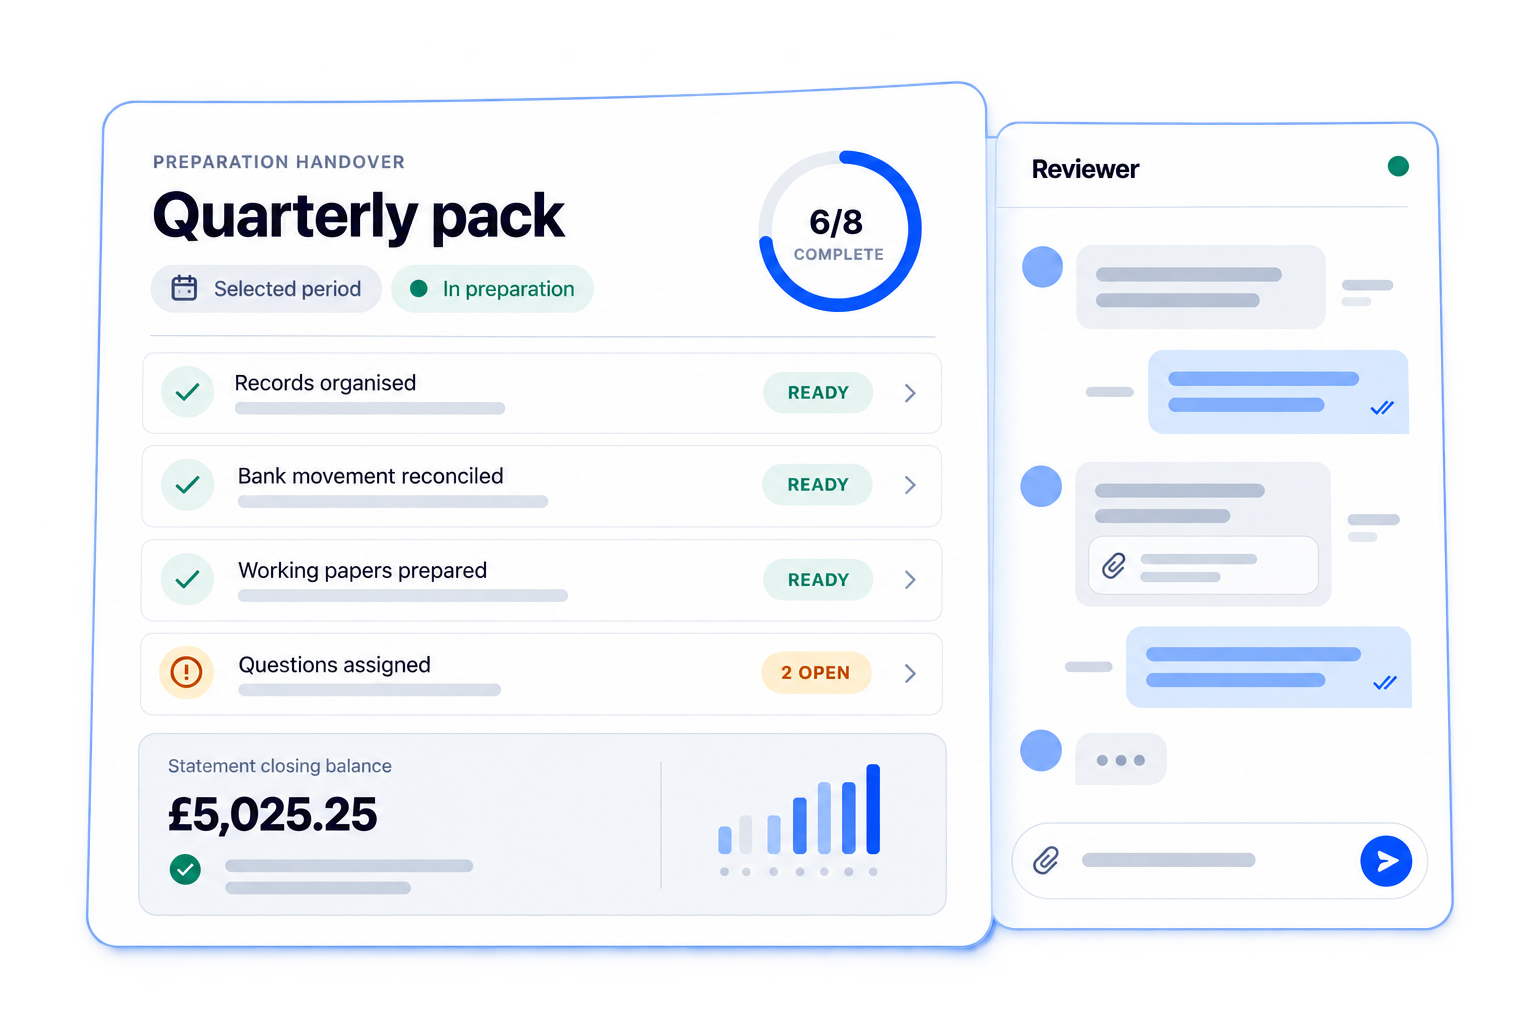
Maacki prepares bookkeeping records, reconciliations and working papers in your approved systems. Your firm reviews, decides and submits.
The capacity problem
When records arrive together, experienced reviewers lose time organising inputs, chasing gaps and rebuilding basic working papers.
Maacki adds a defined preparation layer underneath your reviewers—without moving tax judgement or submission outside your firm.
Who we work with
Maacki is designed for UK accountancy firms with repeatable bookkeeping and MTD preparation work—not for one-off tax advice or legacy clean-up.
Protect senior review time when quarterly preparation starts consuming the working week.
Add a controlled preparation layer before committing to another permanent hire.
Standardise reconciliations, working papers and exception handovers across recurring work.
Create one visible preparation format while each office keeps its own reviewer control.
A controlled start
Start small enough to inspect the work, the controls and the reviewer effort.
Choose one quarter, the source types, your reviewer and a written acceptance checklist.
Confirm contracts, named users, India access, approved systems and data-handling policies.
Measure preparation time, reviewer effort and open questions before reserving capacity.
A handover your reviewer can inspect
Defined pilot · no monthly commitment
Scope and timing are confirmed after reviewing your aggregate workload, record condition and access requirements.
Up to 10 agreed simple income sources or 20 delivery hours, whichever comes first.
After a successful sample
Monthly desks are a separate agreement. Extra work always needs approval.
£1,250 / month
£1,950 / month
£2,750 / month
Applicable taxes and commercial terms are confirmed in your quote.
Common questions
Your firm. Maacki prepares the agreed records and handover. Your reviewer retains professional review, tax judgement and submission responsibility.
By an India-based team. Location, named access and applicable data arrangements are agreed with your firm before any client-data work begins.
For scoping, it usually means one currency and bank feed, up to 100 quarterly transactions, digital records, no inventory or payroll, and no unresolved opening-balance rebuild. This is an internal guide, not an HMRC definition.
Tax returns, independent tax advice, legacy clean-up and unresolved opening-balance reconstruction are outside the sample-quarter scope.
No. Share only your software, aggregate workload and preferred timing. Please do not email client records or credentials.
Start with aggregate figures
Tell us your software, approximate source count and preferred quarter. Please do not send client records.
Discuss a sample quarter